A refrigerated load rejected at a receiver, a pallet shortage discovered after delivery, or electronics damaged in transit can turn one routine run into a costly dispute. Cargo claims affect more than the value of freight. They can strain a carrier’s relationship with a broker or shipper, tie up cash flow, trigger insurance reporting, and affect future load opportunities.
For owner operators and fleets, the goal is not simply to carry cargo coverage and hope for the best. It is to understand what creates a claim, what the carrier must do when one is reported, and where insurance coverage, contractual liability, and federal law may not line up.
What Are Cargo Claims?
A cargo claim is a demand for payment alleging that freight was lost, damaged, delayed, or delivered short while in a motor carrier’s custody. Claims can arise from a collision, theft, fire, improper securement, reefer temperature issues, water intrusion, handling damage, or a missing piece count.
For many interstate shipments, the Carmack Amendment establishes a carrier’s liability framework. In general terms, a shipper must show that the freight was tendered to the carrier in good condition, arrived damaged or short, and resulted in a measurable loss. The carrier may have defenses, but those defenses are fact-specific and should not be assumed just because the driver did not cause a crash.
The bill of lading, rate confirmation, broker-carrier agreement, shipping instructions, temperature records, photographs, and delivery receipt often matter as much as the initial allegation. A signed clean delivery receipt can be helpful, but it does not automatically end every claim. Concealed damage may be discovered after unloading.
Cargo insurance is not the same as cargo liability
Motor truck cargo insurance is designed to respond to covered liability for cargo loss or damage, subject to the policy’s limits, deductibles, exclusions, and conditions. It is not a blank check for every commercial dispute involving a load.
A carrier can also accept liability in a contract that goes beyond what its cargo policy covers. For example, a broker agreement may impose specific temperature-monitoring requirements, strict reporting deadlines, broad indemnification language, or liability for consequential losses. A carrier that signs those terms without reviewing its policy may face an uncovered out-of-pocket exposure.
That is why the cheapest cargo policy is not always the lowest-cost decision. Coverage must fit the commodities, operating radius, trailer type, customer requirements, and contracts the carrier actually accepts.
The First Hours After a Cargo Loss Matter
When freight is damaged, missing, compromised, or rejected, fast and disciplined reporting protects the carrier’s position. Do not dispose of damaged product, authorize a salvage sale, admit fault, or agree to a claim amount before the facts and insurance requirements are reviewed.
Start by securing the equipment and freight. If a collision or theft occurred, involve law enforcement when appropriate. Keep the load available for inspection unless the shipper, receiver, insurer, or a qualified surveyor provides direction otherwise. Perishable freight can require immediate action, but the carrier should document why action was necessary and who authorized it.
The driver should provide a clear timeline while details are fresh. Record pickup and delivery times, seal numbers, trailer condition, reefer set point and actual temperatures, locations, weather, communications, and every person involved in the handoff. Take wide and close photos of the cargo, packaging, trailer interior, securement, damage, and paperwork.
Notify the broker or shipper under the reporting process in the load documents. Then report the incident to the cargo insurer or agency as soon as practical. Late notice can complicate a claim, particularly when an insurer loses the opportunity to inspect freight, investigate a theft, or limit the loss through salvage.
Documentation That Can Defend a Carrier
Good documentation does not manufacture a defense, but poor documentation can make a valid defense nearly impossible to prove. Drivers and dispatch staff need a consistent process, not a scramble after the receiver refuses a load.
For each shipment, retain the signed bill of lading, rate confirmation, pickup and delivery receipts, lumper tickets, scale tickets when relevant, seal records, and dispatch communications. For temperature-controlled freight, retain pre-cool records, continuous temperature downloads, reefer fuel records, alarm history, and any temperature instructions provided by the shipper.
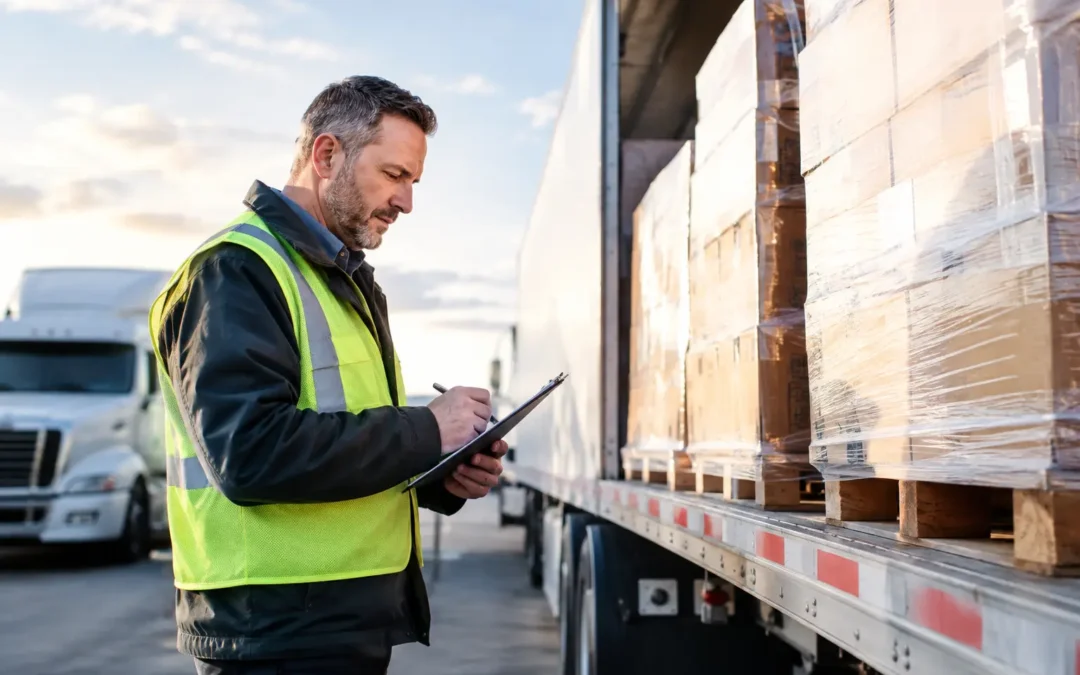
At pickup, the driver should inspect visible packaging, count freight when feasible, verify pallet condition, confirm seal information, and note exceptions on the bill of lading. If the freight is loaded and sealed by the shipper, the driver should not guess about internal count or condition. The paperwork should accurately reflect the circumstances, such as “shipper load and count” when applicable.
At delivery, do not sign paperwork that inaccurately states the cargo was received in good order if there is visible damage, a shortage, or a temperature exception. Ask the receiver to identify the issue in writing. If they refuse to document it, the driver should make a factual note on the delivery receipt and notify dispatch immediately.
Common Cargo Claim Problems for Small Fleets
Some cargo losses are obvious: a rollover, trailer theft, or a major reefer failure. Others develop from ordinary operational gaps that compound quickly.
Improper securement can crush, shift, or topple freight even when the truck reaches delivery without an accident. Water damage can come from a worn door seal, roof leak, or a trailer left open at a dock. Theft exposure rises when drivers park loaded trailers in unsecured locations or leave keys, seals, and dispatch information poorly controlled.
Reefer loads present a separate layer of risk. A carrier may be blamed for a temperature rejection even when the issue began before pickup, the product was loaded warm, or the shipper provided incomplete instructions. The defense depends on records. Without pre-trip inspection notes, set-point confirmation, temperature downloads, and communication logs, it becomes much harder to separate a carrier-caused issue from a product or loading issue.
High-value commodities require special attention. Electronics, pharmaceuticals, alcohol, apparel, and certain food products may need higher cargo limits, specific security protocols, unattended-vehicle restrictions, or specialized endorsements. A standard $100,000 cargo limit may satisfy one broker’s certificate requirement yet be inadequate for a single full load.
Responding to a Formal Cargo Claim
A complaint by phone or email is not always a properly presented cargo claim, but it should still be taken seriously. Under the Carmack framework, carriers generally must allow at least nine months for a shipper to file a written claim and at least two years to bring a civil action after a written claim denial. The actual deadlines and obligations can vary based on the shipment, contract, and governing law, so do not rely on a general rule without reviewing the documents.
A proper written claim should identify the shipment, describe the alleged loss or damage, and demand a specific or determinable amount of money. Send the claim promptly to the cargo insurer or claims administrator. Preserve all evidence, cooperate with the investigation, and keep communications professional and factual.
Do not make admissions such as “our driver caused the damage” before the investigation is complete. That does not mean ignoring the customer or being evasive. It means acknowledging receipt, advising that the matter is under review, and providing information through the appropriate claims process.
The insurer may appoint an adjuster, request a cargo inspection, review invoices and salvage value, or ask for driver statements and equipment maintenance records. The carrier should participate fully while avoiding independent settlements that could interfere with the policy’s settlement and consent provisions.
Building a Cargo Program That Matches Your Freight
Cargo protection starts before dispatch accepts the load. Fleet owners should review the commodities they haul, their largest expected shipment values, theft exposure, trailer equipment, authority, lanes, and customer contract requirements. A carrier moving dry grocery from distribution center to distribution center has different exposures than a reefer operation hauling produce across state lines or a port drayage carrier moving containers.
Ask direct questions when placing or renewing coverage: Are unattended vehicle thefts covered? Are temperature losses covered, and what documentation is required? Does the policy exclude certain high-value commodities? Is there a protective safeguards requirement for tracking devices or alarms? Does the limit apply per vehicle, per occurrence, or both? What deductible can the business realistically absorb?
Monarca Trucking Insurance Services helps trucking operators evaluate cargo coverage alongside primary liability, physical damage, and the operational requirements of their authority. The right policy should support the freight you haul, not just produce a certificate that gets the load booked.
A cargo claim does not have to become a business-ending event. Put the right coverage in place, train drivers to document exceptions, and treat every pickup and delivery record as if it may need to tell the story months later. That discipline protects your freight, your revenue, and the relationships that keep your trucks moving.