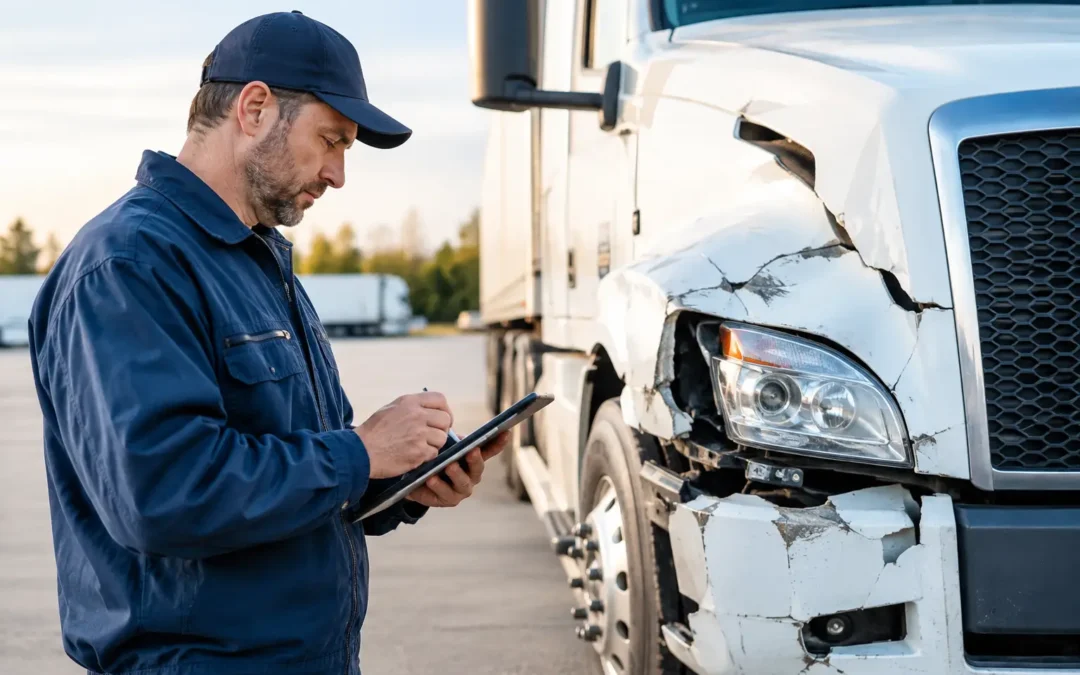
A tractor that is valued wrong can create a costly surprise after an accident, theft, fire, or rollover. This physical damage valuation guide helps owner operators and fleet owners set a realistic insured value before a claim puts that number to the test. The goal is straightforward: carry enough coverage to protect the equipment your business depends on without paying premium for a number that does not reflect the truck’s real value.
Why truck valuation affects more than your premium
Physical damage insurance generally protects your owned equipment against covered direct losses, including collision, comprehensive losses such as theft, fire, vandalism, hail, and animal strikes, and sometimes specified perils depending on the policy. It is different from primary auto liability, which responds to injury or property damage you cause to others.
The insured value influences physical damage premium, but it also sets expectations for the maximum amount available after a total loss. If a truck is insured far below its actual market value, the lower premium may look attractive until the settlement does not provide enough money to replace the unit, pay off a lender, or get back on the road.
Overvaluing a truck has a different downside. You may pay more premium than necessary, and most physical damage policies do not turn a loss into a profit. The carrier will still apply the valuation terms, deductibles, salvage value, policy conditions, and the vehicle’s actual pre-loss value.
For a working carrier, valuation is a business continuity decision. A tractor sitting totaled in a storage yard does not produce revenue, and a delayed replacement can mean missed loads, unhappy brokers, and pressure on cash flow.
Physical damage valuation guide: know your policy basis
The declarations page may show a stated amount or scheduled value for each power unit and trailer. That number matters, but it does not automatically tell you exactly what a total-loss check will be. Read the loss settlement language in the policy and ask how the carrier determines value at the time of loss.
Actual cash value
Actual cash value, often called ACV, is common in commercial trucking physical damage coverage. In practical terms, it is the truck’s fair market value immediately before the covered loss, subject to the policy limit and deductible.
Carriers may consider comparable truck sales, year, make, model, mileage, engine, transmission, condition, prior damage, maintenance, and regional market conditions. A clean 2022 sleeper with a documented overhaul and desirable specs may command more than another truck of the same year with high mileage or deferred maintenance.
ACV can be reasonable for established equipment, but it requires the scheduled value to keep pace with the market. If used-truck values rise sharply and the policy schedule has not been updated, the unit may be underinsured when it matters most.
Stated amount or scheduled value
A stated amount is the value shown for the unit on the policy schedule. It is often the maximum amount the insurer will pay before the deductible, but the exact settlement can depend on the policy wording. Some forms pay the lesser of actual cash value, cost to repair or replace, or the stated amount.
That distinction matters. Scheduling a tractor at $170,000 does not necessarily mean a $170,000 payment if its supportable pre-loss market value is lower. On the other hand, scheduling that same tractor at $115,000 can create a hard ceiling even if comparable replacement units cost substantially more.
Do not assume the word “stated” means “agreed.” Ask your broker to confirm whether the policy uses stated amount, actual cash value, or a true agreed-value endorsement.
Agreed value
Agreed value coverage is less common and may be subject to specific underwriting requirements. When available, it can provide more certainty because the insurer and insured agree on the unit’s value before a covered total loss, subject to policy terms.
This option can make sense for specialty equipment, restored units, low-mileage trucks with major upgrades, or equipment with limited comparable sales. It may cost more, and it still does not replace the need to understand exclusions, deductibles, and loss conditions.
How to establish a defensible truck value
The best valuation is not based on what you paid years ago, what you still owe, or what you hope to receive if you sell. It should reflect the current replacement market for equipment with similar specifications and condition.
Start with the truck’s basic identity: VIN, year, make, model, mileage, engine, transmission, axle configuration, sleeper size, and emissions system. Then look at current dealer inventory and recent comparable sales for similar trucks, not just broad online price ranges. A day cab used for local container work should not be compared blindly with a long-haul sleeper that happens to share a model year.
Condition is where many valuations go wrong. Keep maintenance records, inspection reports, tire invoices, photographs, and repair documentation. Major repairs can support value, especially an engine rebuild, transmission replacement, emissions-system work, new tires, or a documented preventive maintenance program. But not every dollar spent on repairs adds a dollar to market value. Maintenance preserves the truck’s condition; it does not always create a higher resale price.
For trailers, consider the same details. Type, age, dimensions, reefer unit hours, liftgate, suspension, flooring, lining, ramps, and specialized securement equipment all affect value. A dry van, refrigerated trailer, flatbed, lowboy, and chassis should be scheduled separately at values that match their actual exposure.
Do not confuse loan balance with insurance value
A lender’s payoff amount and a truck’s market value often move in different directions. You may owe more than the truck is worth after a down payment with limited equity, a long finance term, or a sudden decline in used-equipment prices. That difference is a financing problem, not a reason to inflate the physical damage value.
If the truck is financed or leased, review the lender’s insurance requirements. Many require physical damage coverage and may require the lender or lessor to be listed correctly as loss payee. If a total loss could leave a payoff balance after the insurance settlement, ask about gap coverage or similar protection if it is available and appropriate for your financing arrangement.
The same principle applies to owner operators leased to a motor carrier. The lease agreement may require you to carry physical damage, but the unit should still be scheduled based on the policy’s valuation terms and the truck’s supportable value.
Account for upgrades, attached equipment, and exclusions
A tractor is rarely just a factory-spec tractor. APUs, headache racks, custom bumpers, toolboxes, inverters, extra fuel tanks, lift axles, tarping systems, and permanently attached equipment may add meaningful value. Some items may be included only up to a limited amount, while others need to be specifically scheduled.
Cargo is not physical damage. Freight, customer-owned property, and many detachable tools require separate coverage analysis under motor truck cargo, inland marine, or another applicable policy. Personal belongings inside the cab can also be subject to limited coverage or exclusions.
Before binding or renewing coverage, confirm what is included for attached equipment, electronics, custom parts, towing after a covered loss, storage charges, and rental reimbursement or downtime-related options. Coverage details vary by carrier, vehicle class, and operation.
Review values at renewal and after major changes
A once-a-year review is the minimum. Review scheduled values sooner when you buy a unit, pay for a major upgrade, change from local hauling to long-haul operation, add specialized trailers, refinance equipment, or see major movement in the used-truck market.
For fleets, create a unit-by-unit equipment schedule that matches the vehicles actually in service. VIN errors, retired units left on the policy, and newly acquired trailers that were never reported can create claim and audit problems. Keep purchase documents and updated photos in one place so you can provide them quickly when a claim occurs.
New ventures should be especially careful. The pressure to control startup premium can lead to low scheduled values, high deductibles, or coverage gaps that are hard to absorb during the first major loss. A higher deductible can be a sound choice if the business has cash reserves. It is not a substitute for accurately valuing the equipment.
Questions to ask before you bind coverage
Ask whether the policy settles total losses on actual cash value, stated amount, agreed value, or the lesser of several amounts. Confirm whether the scheduled value is a maximum payout, how comparable values are determined, and whether upgrades are automatically included or must be scheduled.
Also ask what deductible applies to collision, comprehensive, theft, and glass losses. A $5,000 or $10,000 deductible may fit a fleet with strong reserves, but it can put an owner operator in a difficult position after a repairable loss. Finally, confirm the loss payee wording required by your lender and whether the policy meets your lease or contract requirements.
The right number is not the lowest value that produces an acceptable quote. It is the value you can document and rely on when the truck that keeps your authority moving is suddenly out of service. A trucking-focused insurance review can help match that number, the policy wording, and your deductible to the way your operation actually runs.